UAE issues major tax rule change from January 1, 2026
The UAE has introduced significant updates to its tax procedures framework with the issuance of Federal Decree-Law No. (17) of 2025, amending key provisions of Federal Decree-Law No. (28) of 2022 on Tax Procedures.…
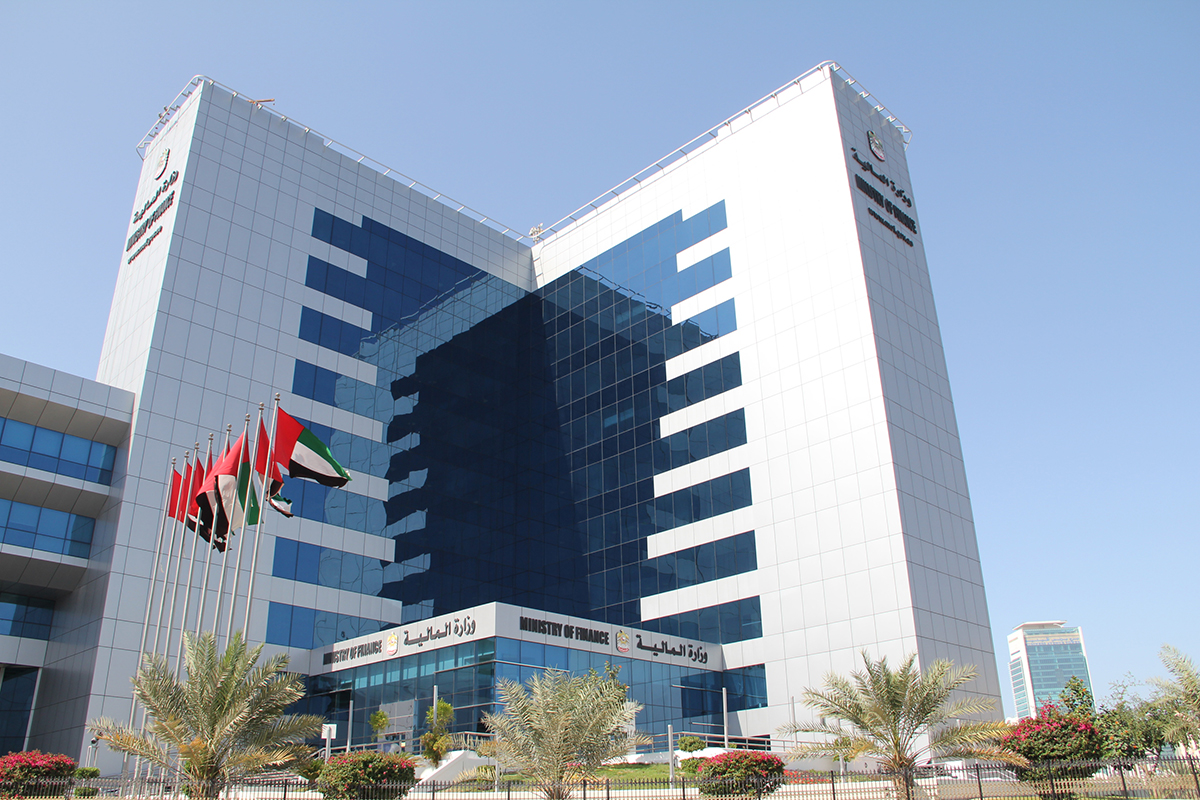
The UAE has introduced significant updates to its tax procedures framework with the issuance of Federal Decree-Law No. (17) of 2025, amending key provisions of Federal Decree-Law No. (28) of 2022 on Tax Procedures.
The Ministry of Finance confirmed that the new law will take effect on January 1, 2026.
The amendments improve efficiency, enhance clarity for taxpayers, and strengthen transparency, fairness and financial discipline across the UAE’s tax system.
UAE tax rules
A central component of the amendments is a defined period—not exceeding five years from the end of the relevant tax period—for taxpayers to request a refund of a credit balance from the Federal Tax Authority (FTA) or apply that balance toward outstanding tax liabilities.
The framework also offers added flexibility in specific cases, enabling taxpayers to submit refund requests if a credit balance arises after the five-year period or within the final ninety days of that window.
According to the Ministry, this approach strengthens financial certainty and better organises tax-related processes.

Federal Tax Authority regulations
The amended law also expands the FTA’s powers concerning limitation periods. The Authority may conduct audits or issue tax assessments even after a limitation period has expired in certain circumstances, such as refund requests submitted during the final year of the period.
This aims to strike a balance between protecting taxpayers’ rights and safeguarding the state’s financial entitlements.
Under the new provisions, the FTA may issue official and binding directions—to taxpayers and to the Authority itself—on the application of tax legislation to specific transactions.
This measure is intended to unify interpretation, reduce inconsistencies, and support more effective and practical implementation across the tax system.
Transitional provisions
To ensure fairness and consistency, the amendments introduce transitional measures for taxpayers with credit balances whose five-year period expired before January 1,2026 or is due to expire within one year from that date.
These taxpayers may submit refund requests within one year from January 1, 2026.
They may also file a voluntary disclosure related to the request within two years from the filing date, provided the FTA has not yet issued a decision.
The changes are expected to enhance tax system efficiency, reduce administrative burdens, build trust and transparency, and support sustainable public revenues—contributing to a more competitive business environment and long-term economic growth.
More from Capital & Sovereign Wealth Desk
Abu Dhabi Property Market Draws Institutional Focus
Abu Dhabi’s real-estate market is gaining attention as regulation, demand and sovereign-linked development make the sector more institutional.
Dubai 2040 Brings Liveability Into Growth Debate
Dubai’s long-term urban plan places housing, mobility, public space and district design at the centre of the city’s…
Saudi Logistics Plan Moves From Strategy to Capacity
Saudi Arabia’s logistics agenda is becoming a national competitiveness test as the kingdom works to connect ports, airports,…